SWOT Analysis of OYO Rooms Explained in Detail
A full SWOT analysis of OYO Rooms, written as a sample for MBA and undergraduate business-strategy modules. It covers the asset-light franchise model, quality control across partner hotels, funding and profitability, and competition from Airbnb, Marriott and FabHotels, updated with OYO's FY2025 results, the Prism rebrand and the 2026 IPO clearance.
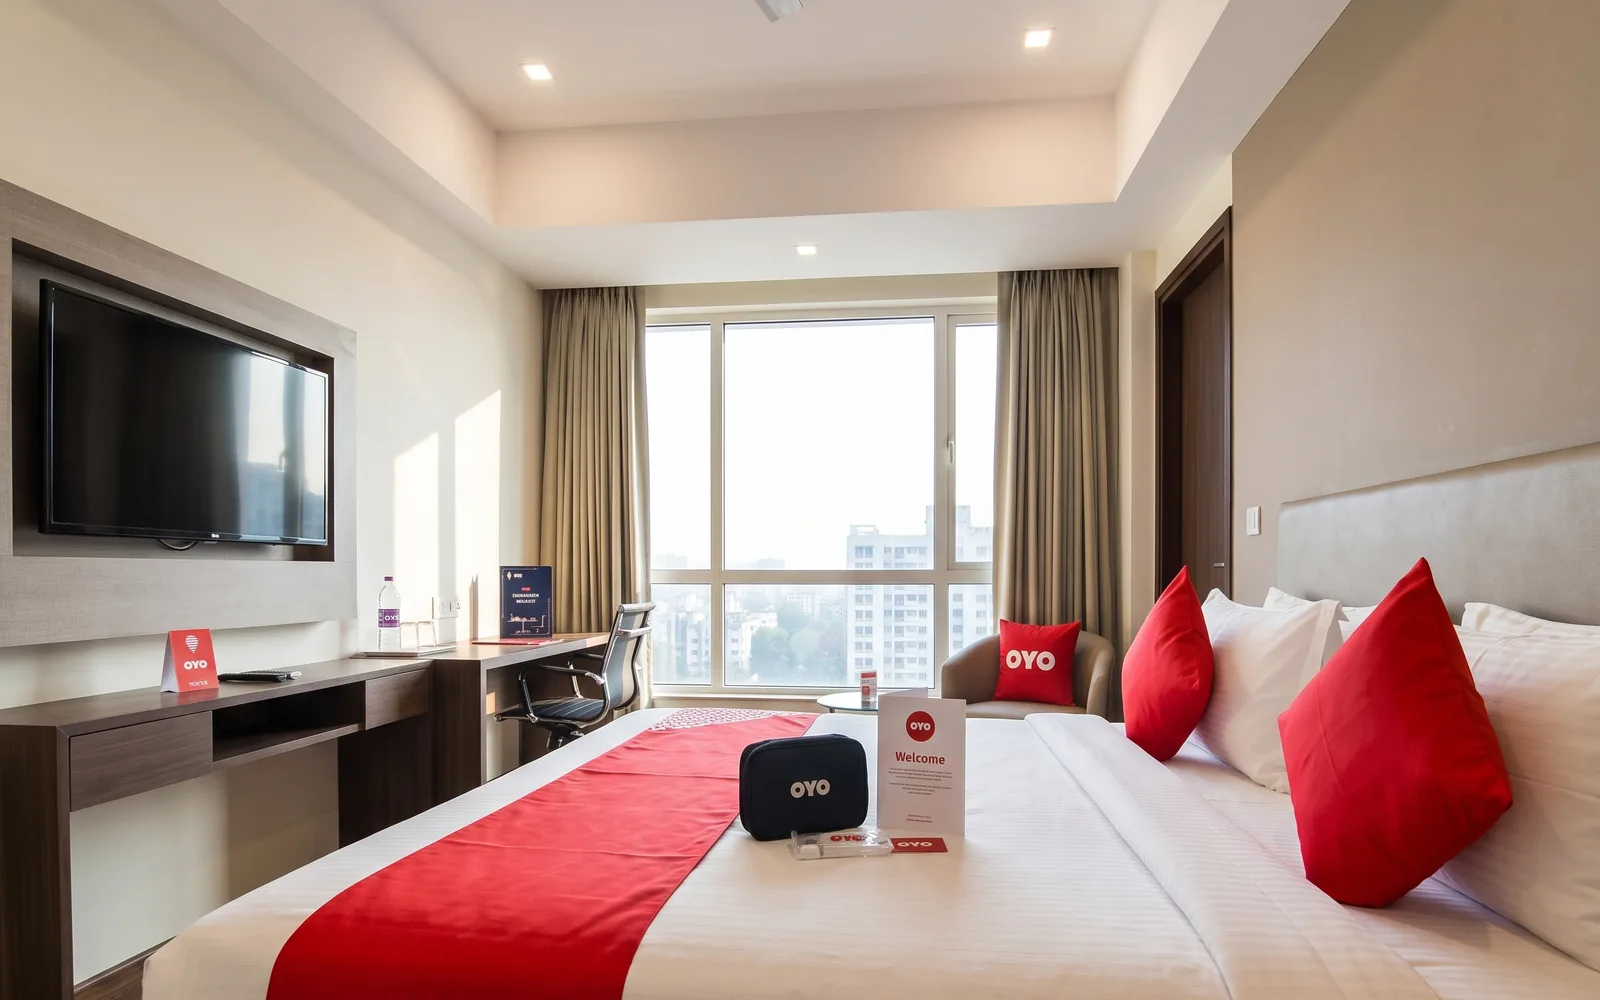
This is a worked SWOT analysis of OYO Rooms, written as a sample for MBA and undergraduate business-strategy modules. It uses the standard four-quadrant SWOT framework and treats OYO as an asset-light hotel aggregator rather than a hotel owner, because that distinction explains most of its strengths and nearly all of its weaknesses. The figures run from the company's 2021 draft prospectus to June 2026, and each one carries its date.
If you are working on a similar brief, our MBA assignment help page explains how we handle strategy case studies, and the MBA assignment samples archive has more of them.
What Does a SWOT Analysis of OYO Rooms Show?
It shows one decision seen from two sides. OYO does not own the hotels it sells: it signs existing small hotels, sets a standard for the room, puts its brand on the front and sells the rooms through its app, while the building and its running costs stay with the owner. Growth and the quality problem both start there.
SWOT analysis of OYO Rooms at a glance
Strengths Internal, helpful
- Asset-light: hotel storefronts rose from 13,000 to 21,000 between March 2023 and March 2025, in buildings it does not own
- Largest hotel-storefront footprint in India and Southeast Asia among full-stack operators (RedSeer, 2021)
- Brands from OYO and Townhouse to Motel 6, in more than 35 countries
- More than 40 tools for hotel owners in two apps, Co-OYO and OYO OS
- Sold through online travel agents and travel management companies as well as its own app
Weaknesses Internal, harmful
- Quality rests on owners who can leave: one hotel group said more than 300 hotels quit in 2019
- Total expenses of 6,659.5 crore rupees above total income of 6,325.9 crore in 2024-25
- A loss every year to 2022-23; the first annual profit, 229.6 crore rupees, rested on exceptional gains
- Brand copied: more than 50 unauthorized 'OYO' hotels sealed in Ghaziabad in January 2025
Opportunities External, helpful
- GST on rooms up to 7,500 rupees a night cut from 12 to 5 percent from 22 September 2025
- A stated shift to higher-yield brands and to religious destinations
- More than 150 Motel 6 and Studio 6 hotels planned for 2025 in the United States
Threats External, harmful
- Chains, Airbnb and aggregators; OYO fined 168.88 crore rupees by India's competition regulator in 2022
- Revenue from customers fell 69.9 percent in the pandemic year 2020-21
- The 5 percent GST comes without input tax credit, raising partner hotels' costs
The company says as much in its 2021 draft prospectus: "We do not own the storefronts listed on our platform." It competes with global chains such as Marriott and Hilton, which have their own budget formats and large loyalty programs, with home-sharing platforms such as Airbnb, and with regional budget aggregators such as FabHotels that chase the same partner hotels. The grid gives each point in a line. The sections below argue each one from a dated source, because a marker gives credit for evidence, not for a list of adjectives.
What Are the Strengths of OYO Rooms?
OYO's strengths come from not owning hotels. Partnering with existing properties lets it add rooms without building any, which its prospectus describes as scaling "with minimal marginal costs". On top of that sit scale in the budget segment, a portfolio that now runs from mid-segment Townhouse hotels to Motel 6, a pricing and booking platform built in-house, and distribution well beyond its own app.
- The asset-light model. OYO sells rooms in hotels somebody else built. Its 2021 draft prospectus listed 157,344 storefronts in more than 35 countries and said 99.9 percent of them had no contract guaranteeing the owner a minimum payment, with investment and staff costs "borne largely by our Patrons", its word for owners (Oravel Stays draft prospectus, September 2021). The model has kept adding rooms: between March 2023 and March 2025 the group's hotel storefronts rose from 13,000 to 21,000 (Oravel Stays annual report 2024-25).
- Scale in the budget segment. The prospectus cited research by RedSeer that put OYO first by hotel storefronts in India and Southeast Asia among full-stack short-stay operators in September 2021, and the annual report says the company served more than 100 million customers as of March 2025. For an unbranded small hotel, that flow of guests is the product OYO is selling to the owner.
- A diversified portfolio. The group's hotel brands run from OYO and the mid-segment Townhouse to Motel 6 and Studio 6 in the United States, and it also operates event venues (Hotel Dive, 9 September 2025). In Europe it sells vacation homes under Belvilla and DanCenter. Different formats mean different price points and less exposure to one segment.
- Technology as the operating system. Pricing, availability, bookings and check-in run through OYO's own systems. The 2021 prospectus counted more than 40 products and services for owners, bundled into two apps, Co-OYO and OYO OS; by 2025 the group was listing hospitality technology, including AI-driven partner tools, as a business of its own. For a partner hotel with no revenue management of its own, this is the measurable part of what it gets, and for OYO it is the source of the demand data its pricing runs on.
- Distribution beyond its own app. Guests can book on OYO's app or through online travel agents, and the prospectus names online travel agents, travel management companies and global distribution systems as strategic partners. That reach matters most where the brand is new. The same prospectus names the cost: the larger the share of bookings those partners bring, the lower OYO's margin.
What Are the Weaknesses of OYO Rooms?
The asset-light model that creates the strengths also creates the weaknesses. OYO controls the brand but not the building, so a stay depends on owners who can leave, and a bad night is blamed on OYO. Its costs have run ahead of its income for most of its history, and in both of its profitable years the profit came from items outside day-to-day trading.
- Quality control through owners who can leave. OYO can set a standard and inspect against it, but the staff and the building belong to the owner, and so does the decision to stay. In 2019 Reuters interviewed 22 owners and managers of OYO hotels in 10 Indian cities, who described fees they discovered only in their monthly statements. The head of one hotel group told Reuters that more than 300 hotels had quit OYO's India network that year, while OYO said it kept 99 percent of its owners (Reuters, via Al Jazeera, 7 October 2019).
- A cost base that ran ahead of income. OYO once guaranteed many owners a minimum payment whatever their rooms earned: such contracts covered 14.7 percent of its storefronts in March 2019 and 0.1 percent by March 2021, according to the prospectus. Cutting them did not close the gap. In the audited accounts for 2024-25, total expenses of 6,659.5 crore rupees were higher than total income of 6,325.9 crore, and finance costs alone came to 959.2 crore.
- A late and thin profit. The prospectus records a loss in every year from incorporation to March 2021, including 13,122.8 crore rupees in 2019-20. The first annual profit came in 2023-24 (Business Standard, 14 August 2024). The audited accounts put it at 229.6 crore rupees, after net exceptional gains of 409.9 crore, without which the year would have shown a loss before tax. That is why the 2024-25 result below needs reading with care.
- Reputation held centrally, service delivered locally. A guest who has a bad night under an OYO sign blames OYO, whoever runs the building. The prospectus lists incidents "mistakenly attributed to us" among its risks, and the sign itself can be copied: in January 2025 OYO said police in Ghaziabad had sealed more than 50 hotels that were using its brand without authorization (Deccan Herald, 8 January 2025).
What Opportunities Does OYO Rooms Have?
The openings worth arguing in an assignment each have a dated event behind them: a lower tax on budget rooms in India from September 2025, the group's stated push into higher-yield brands and religious destinations, and a franchised motel chain to grow in the United States.
- A lower tax on budget rooms. From 22 September 2025 India cut the goods and services tax on hotel rooms priced up to 7,500 rupees a night from 12 percent to 5 percent (News On Air, 2 October 2025). A guest in that band pays less tax on the same room rate, which helps a budget brand compete on price. The catch is that the 5 percent rate comes without input tax credit, and the finance ministry has said hotels in the band cannot choose 18 percent with credit instead (Business Standard, 16 September 2025). The threats section returns to what that costs the owners.
- Higher-yield brands and religious destinations. The 2024-25 annual report describes "a deliberate shift to higher-yield brands such as Sunday, Townhouse, Collection O, and Palette", and says the company added properties in religious destinations as spiritual tourism grew in India. Skift's report on the June 2026 IPO clearance names the same two segments. Higher-yield formats earn more per room and lean less on volume to cover fixed costs.
- A franchised chain in the United States. The G6 Hospitality purchase brought the Motel 6 and Studio 6 brands, and the company said it would add more than 150 hotels under them in 2025 (Hotel Dive, 9 September 2025). A franchised budget chain in a mature market is a different business from an aggregator in India, so the opportunity arrives with an integration risk.
What Threats Does OYO Rooms Face?
OYO is squeezed from three directions at once: global chains moving down into budget formats, home-sharing platforms taking the price-sensitive traveler, and regional aggregators competing for the same partner hotels. Add to that travel demand that can disappear, as it did in 2020, and tax rules that change the economics of its partner hotels without OYO changing anything.
- Competition from three directions. Marriott and Hilton compete with scale and loyalty programs, Airbnb competes on price and character, and regional aggregators such as FabHotels compete for the same independent hotels. Competition law bites as well: in October 2022 India's competition regulator fined OYO 168.88 crore rupees and MakeMyTrip 223.48 crore for anti-competitive behavior, after a hotel body alleged that MakeMyTrip favored OYO on its sites and apps (Skift, 24 October 2022).
- Demand that can vanish. Travel is one of the first things households and companies cut. In the pandemic year OYO's revenue from customers fell 69.9 percent, from 13,168.2 crore rupees in 2019-20 to 3,961.6 crore in 2020-21, according to the prospectus. Currency movements and local downturns do the same on a smaller scale to a business whose revenue is a share of room nights.
- Tax rules that change the partners' economics. Rules change independently in every market OYO enters. In India, the move to 5 percent GST without input tax credit means hotels can no longer offset the tax on what they buy; the Hotel Association of India said the change would be detrimental for budget and mid-scale hotels, which would mostly have to absorb the extra cost (Business Standard, 16 September 2025). A change like that squeezes the owners OYO depends on without touching anything OYO controls.
What Has Changed for OYO Since 2023?
Since 2023 OYO has reported two years of profit, bought an American motel chain, and seen its parent rename itself Prism and win clearance to list. Each of those moves a quadrant, although the profit is smaller in the audited accounts than in the figure first announced.
OYO profit for the year, 2023-24 and 2024-25
Chart data
| Item | Value (crore rupees) |
|---|---|
| 2023-24, audited accounts | 229.6 crore rupees |
| 2024-25, as announced in May 2025 (unaudited) | 623 crore rupees |
| 2024-25, audited accounts | 244.8 crore rupees |
Profit, on two bases. In May 2025 OYO said it had made a profit after tax of about 623 crore rupees in 2024-25, up from 229 crore, on revenue of roughly 6,463 crore; the figures were unaudited (Business Standard, 8 May 2025). The audited consolidated accounts, signed in July 2025, report a profit for the year of 244.8 crore rupees on revenue from operations of 6,252.8 crore. Before tax the group made a loss of 489.3 crore, and a deferred tax credit of 767.6 crore turned it into a profit (Oravel Stays annual report 2024-25). In an assignment, quote the audited figure and say so; if you use the announced one, label it unaudited. The weakness called "a late and thin profit" stands.
A new parent, and a group of brands. In September 2025 the parent company Oravel Stays renamed itself Prism. OYO, Townhouse, Sunday and Palette sit under the new corporate name, while Motel 6 and Studio 6, bought from Blackstone for 525 million dollars at the end of 2024, continue to trade as separate brands with their own market positions (Hotel Dive, 9 September 2025). For a SWOT this matters because "the brand" is no longer one thing.
An IPO, at the third attempt. In June 2026 India's market regulator cleared Prism to proceed with an initial public offering, with press reports putting the expected valuation at 7 to 8 billion dollars (Skift, 2 June 2026). It is the third attempt: the prospectus first filed in 2021 did not proceed, a second filing made in March 2023 was withdrawn in May 2024 while the company refinanced (Skift, 22 May 2024), and this is the filing that has now been cleared. A listing sharpens the regulatory threat: quarterly disclosure, and analysts who will price the quality-control problem.
For the external-factor side of the same company, read the PESTEL analysis of OYO, which covers the political, economic and legal forces this SWOT only touches.
Conclusion
Read as a whole, the matrix says one thing: OYO's strengths and weaknesses are the same decision seen from two sides. Not owning the hotels is what allowed the company to grow quickly and what stops it guaranteeing the product. The return to profit and the move into franchised American motels add scale, but neither changes the quality-control problem, because that sits in buildings the group still does not own, and the audited accounts show that the profit is not yet coming from operations.
Three strategies follow from that reading:
- Enforce the standard. Inspection, mystery shopping and the willingness to remove a property from the brand are the only levers an aggregator has over quality. They cost money and reduce the room count, which is why they are hard to sustain.
- Earn the profit from operations. A profit that depends on a tax credit or an exceptional gain is not yet a trend. Holding one that survives without them means resisting the volume growth that historically came at negative margin.
- Manage the brand architecture. With OYO, Townhouse, Sunday, Palette, Motel 6 and Studio 6 in one group, the risk is that a problem in one name is read as a problem in all of them.
If you are writing this up, finish with the recommendation rather than the matrix. A SWOT that stops at four lists rarely scores well; the marks are in what you decide from it.
Related samples: SWOT analysis of Alphabet, SWOT and PESTEL analysis of WeWork for another asset-heavy-versus-asset-light argument, and Zara PESTLE and VRIO analysis for a worked internal-resource framework. The gap between OYO's announced profit and its audited consolidated profit is the worked example in our guide to reading an annual report for a case study.
Need help with a similar SWOT analysis assignment? Message us on WhatsApp with the company, the framework your brief asks for and your deadline, and we will tell you what we can do.
Sources
- Al Jazeera (7 October 2019). Heartbreak hotel: Is SoftBank's Oyo hurting Indian hoteliers? Reuters report. aljazeera.com (22 owners and managers in 10 cities, more than 300 hotels leaving in 2019, OYO's 99 percent retention figure)
- Oravel Stays Limited (30 September 2021). Draft Red Herring Prospectus. Filed with the Securities and Exchange Board of India. sebi.gov.in (157,344 storefronts, 99.9 percent without minimum guarantees, 14.7 to 0.1 percent with them, losses since incorporation, revenue for 2019-20 and 2020-21, the RedSeer ranking, Co-OYO and OYO OS, distribution partners, risk factors)
- Skift (24 October 2022). India Competition Watchdog Hits MakeMyTrip and Oyo With $47 Million in Sanctions. skift.com
- Skift (22 May 2024). Oyo Pauses IPO, Plans to Refile After Refinancing. skift.com (the March 2023 filing withdrawn in May 2024)
- Business Standard (14 August 2024). Oyo posts first-ever annual profit of Rs 229 crore in FY24, eyes expansion. business-standard.com
- Deccan Herald (8 January 2025). OYO claims Ghaziabad Police cracks down on 'fraud' hotels using its brand. deccanherald.com
- Business Standard (8 May 2025). OYO most profitable startup in FY25 with ₹623 cr profit: Ritesh Agarwal. business-standard.com (the unaudited 2024-25 figures)
- Oravel Stays Limited (23 July 2025). Annual Report 2024-25. oyo-investor-relations PDF (audited consolidated statement of profit and loss for 2024-25 and 2023-24; exceptional items, note 50; storefront growth, customers, brands and strategy in the company overview)
- Hotel Dive (9 September 2025). OYO parent company Oravel Stays rebrands to Prism. hoteldive.com (brand structure, event venues and technology, more than 35 countries, the 525 million dollar G6 Hospitality purchase, more than 150 Motel 6 and Studio 6 hotels planned for 2025)
- Business Standard (16 September 2025). No ITC for hotel rooms up to Rs 7,500 under 5% GST, says FinMin. business-standard.com
- News On Air (2 October 2025). Government cuts GST on budget hotels, art ware and buses to boost tourism. newsonair.gov.in (rooms up to 7,500 rupees moved from 12 to 5 percent from 22 September 2025)
- Skift (2 June 2026). Oyo-Parent Prism Gets Green Light From Indian Regulator for IPO. skift.com (regulator clearance, the 7 to 8 billion dollar valuation, the third attempt, premium and religious tourism)
Frequently Asked Questions
What is the SWOT analysis of OYO Rooms?
OYO's strengths are an asset-light model that let it list more than 157,000 storefronts by 2021 without owning them, a leading hotel footprint in India and Southeast Asia, brands that run up to Motel 6, and its own software for hotel owners. Its weaknesses are uneven quality in owner-run hotels, costs above income and a thin profit. Opportunities include India's 2025 GST cut and premium formats. Threats include rival chains, Airbnb, aggregators and demand shocks.
What are OYO's biggest weaknesses?
The central weakness is quality control. OYO does not own the hotels it sells, so cleanliness, service and amenities vary between partner properties, owners can leave, and one poor stay damages the whole brand. The other weakness is financial: the group lost money every year until 2023-24, and its audited 2024-25 accounts show a loss before tax, with the reported profit coming from a deferred tax credit.
Is OYO profitable?
On its audited accounts, narrowly. Consolidated profit for 2024-25 was 244.8 crore rupees, against 229.6 crore the year before, but the group made a loss before tax and the profit came from a deferred tax credit. The 623 crore figure reported in May 2025 came from unaudited accounts, so say which basis you quote.
Who are OYO's main competitors?
OYO competes on three fronts. Global chains such as Marriott and Hilton compete on trust and loyalty programs, and have moved into budget formats. Airbnb and other home-sharing platforms compete on price and personality. Regional budget aggregators such as FabHotels compete directly for the same partner hotels in India.
How do I write a SWOT analysis of OYO for an assignment?
Set the scope first: one market, one year, one decision. Put each point in the quadrant it belongs in, evidence it with a dated source, then finish with a paragraph that turns the matrix into a recommendation. A SWOT that only lists points scores badly; markers want the strategic conclusion you draw from them.